
 Pavel Hála
Quarterly macro outlook and review
We’ve just released the new Quarterly Macro Outlook, covering the latest trends in interest rates, inflation, and the labor market, as well as the outlook for equities, crypto, and major commodities.
In addition to the new outlook, I’ve recorded a special video reviewing the conclusions and top opportunities I presented in the previous Quarterly Macro Outlook on July 1, exactly three months ago. In the second half of the video, I’ll walk you through part of the new Macro Outlook and explain the latest trends in macroeconomic data.
If you don’t want to watch the video, I’ve summarized my review of the previous macro outlook below.
My main macro conclusion was that the real US economy was strong and would continue to accelerate. That was spot on: money flowed from financial markets into the real economy, and yields pushed higher over the past quarter.
Despite this rotation, I remained bullish on broad indices such as the S&P 500 and Nasdaq. I was only half-right on this one. Yes, the S&P 500 continued to drift higher, and there was no major correction of 10+%.
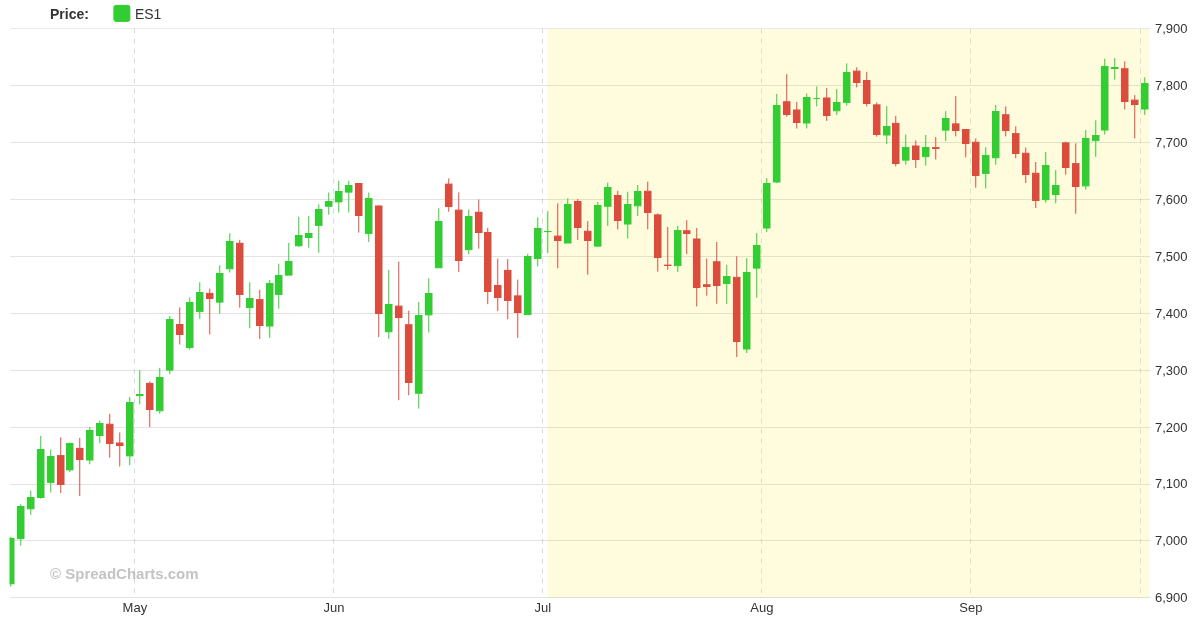
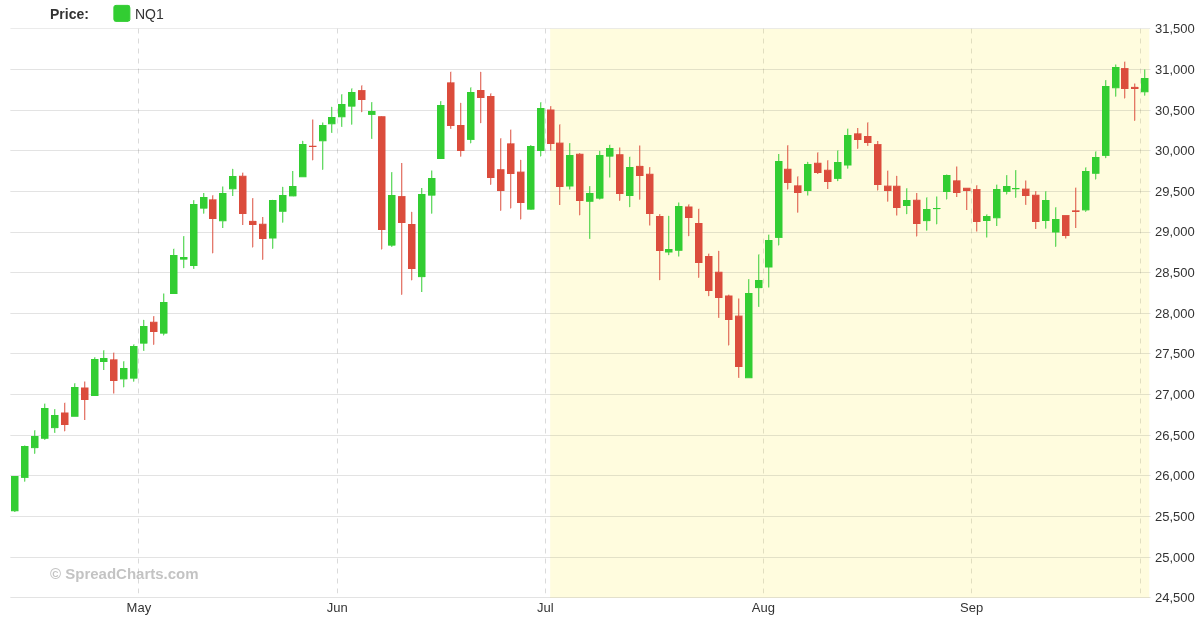
However, I was wrong to expect the Nasdaq to outperform. It has clearly lagged the market, suffered a larger drawdown in July, and is roughly flat for the quarter.
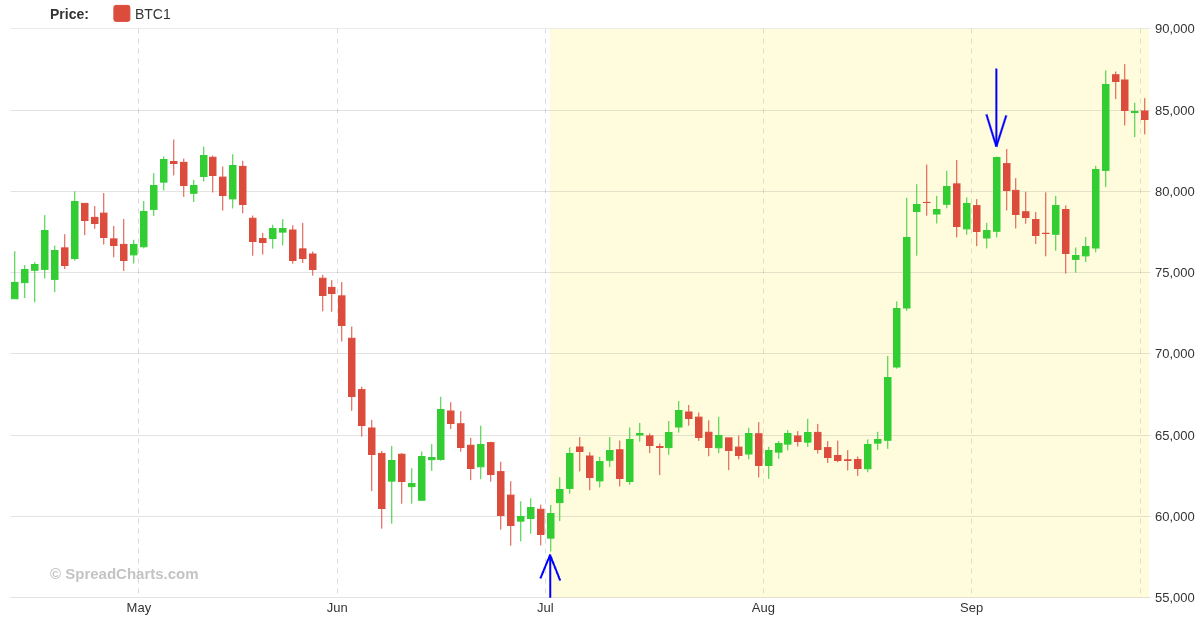
One of my top opportunities that really smashed it was Bitcoin. Everyone was bearish in July, citing quantum risk and the impact of rising rates driven by elevated energy prices. I faded all of that, and the result was spectacular.
Bitcoin rallied from below $60k to $87k, and I personally closed my crypto positions (ETF options) on the spike to $82k.
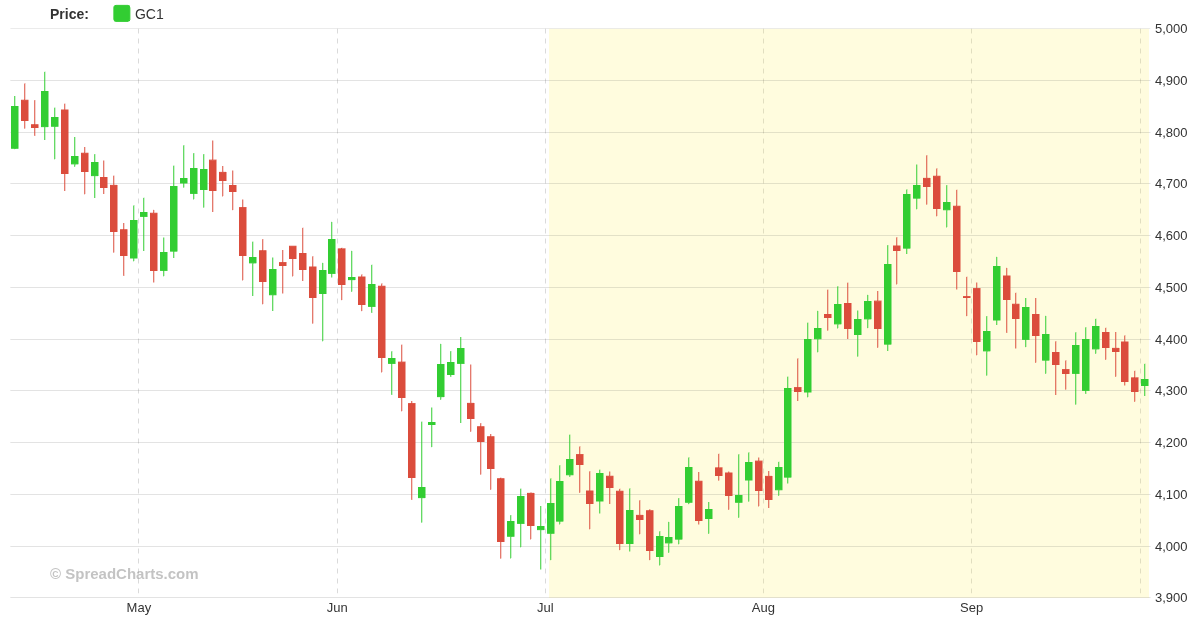
Another top opportunity was gold. It rallied less than Bitcoin and gave back much of its gains in September. Still, the move from $4,000 to $4,700 was significant, so I consider this a success.
One area where I was wrong was oil. I reiterated my long-term bullish view but expected more consolidation in the near term, mainly because of the sustained decline in backwardation. That wasn’t what happened. Oil started moving higher immediately.
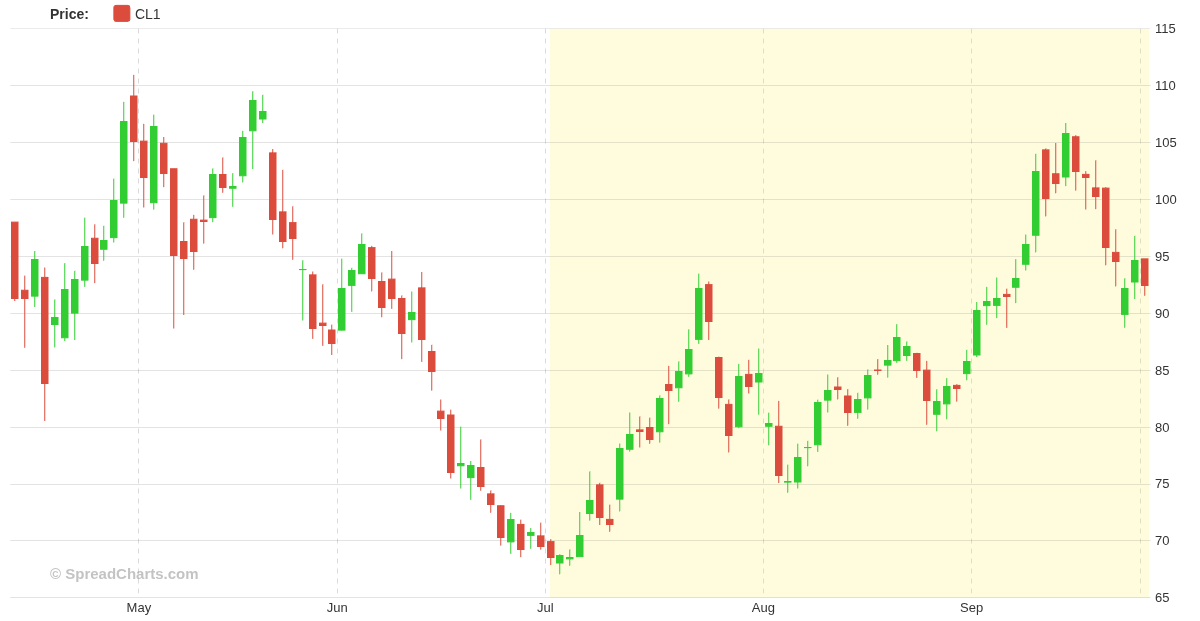
I suspect the main catalyst was the collapse of the memorandum of understanding between the US and Iran. Frankly, I thought it would hold for at least a few months, probably until the midterms, with the war resuming only after that. But geopolitics is tricky, and while Iran’s foreign ministry wanted to stick to the deal, the IRGC sabotaged it with strikes on tankers.
So, that was the past quarter.
Today, we’ve released our new Quarterly Macro Outlook for the fourth quarter of 2026. It’s our core analysis, so don’t miss it. Some very interesting opportunities are emerging, and I suspect people will be surprised by where I see some key markets heading in the coming months.
Check out these great articles as well
Pavel HálaNormalized COT
We added a neat new feature for Commitments of Traders data. You can now normalize...
Read morePavel HálaNew data: Rates and electricity
As promised, we’re adding new data to the SpreadCharts app. Importantly, the goal is not...
Read morePavel HálaNew data: Sector indices
Our software is already established well beyond commodity market analysis. Stock indices, currencies, and even...
Read morePavel HálaWhat’s new in the SpreadCharts app?
It’s been a few months since we launched the new version of the SpreadCharts app....
Read more